Buying a House With Family? Have These Conversations Before Thanksgiving Dinner Turns Into a Deal
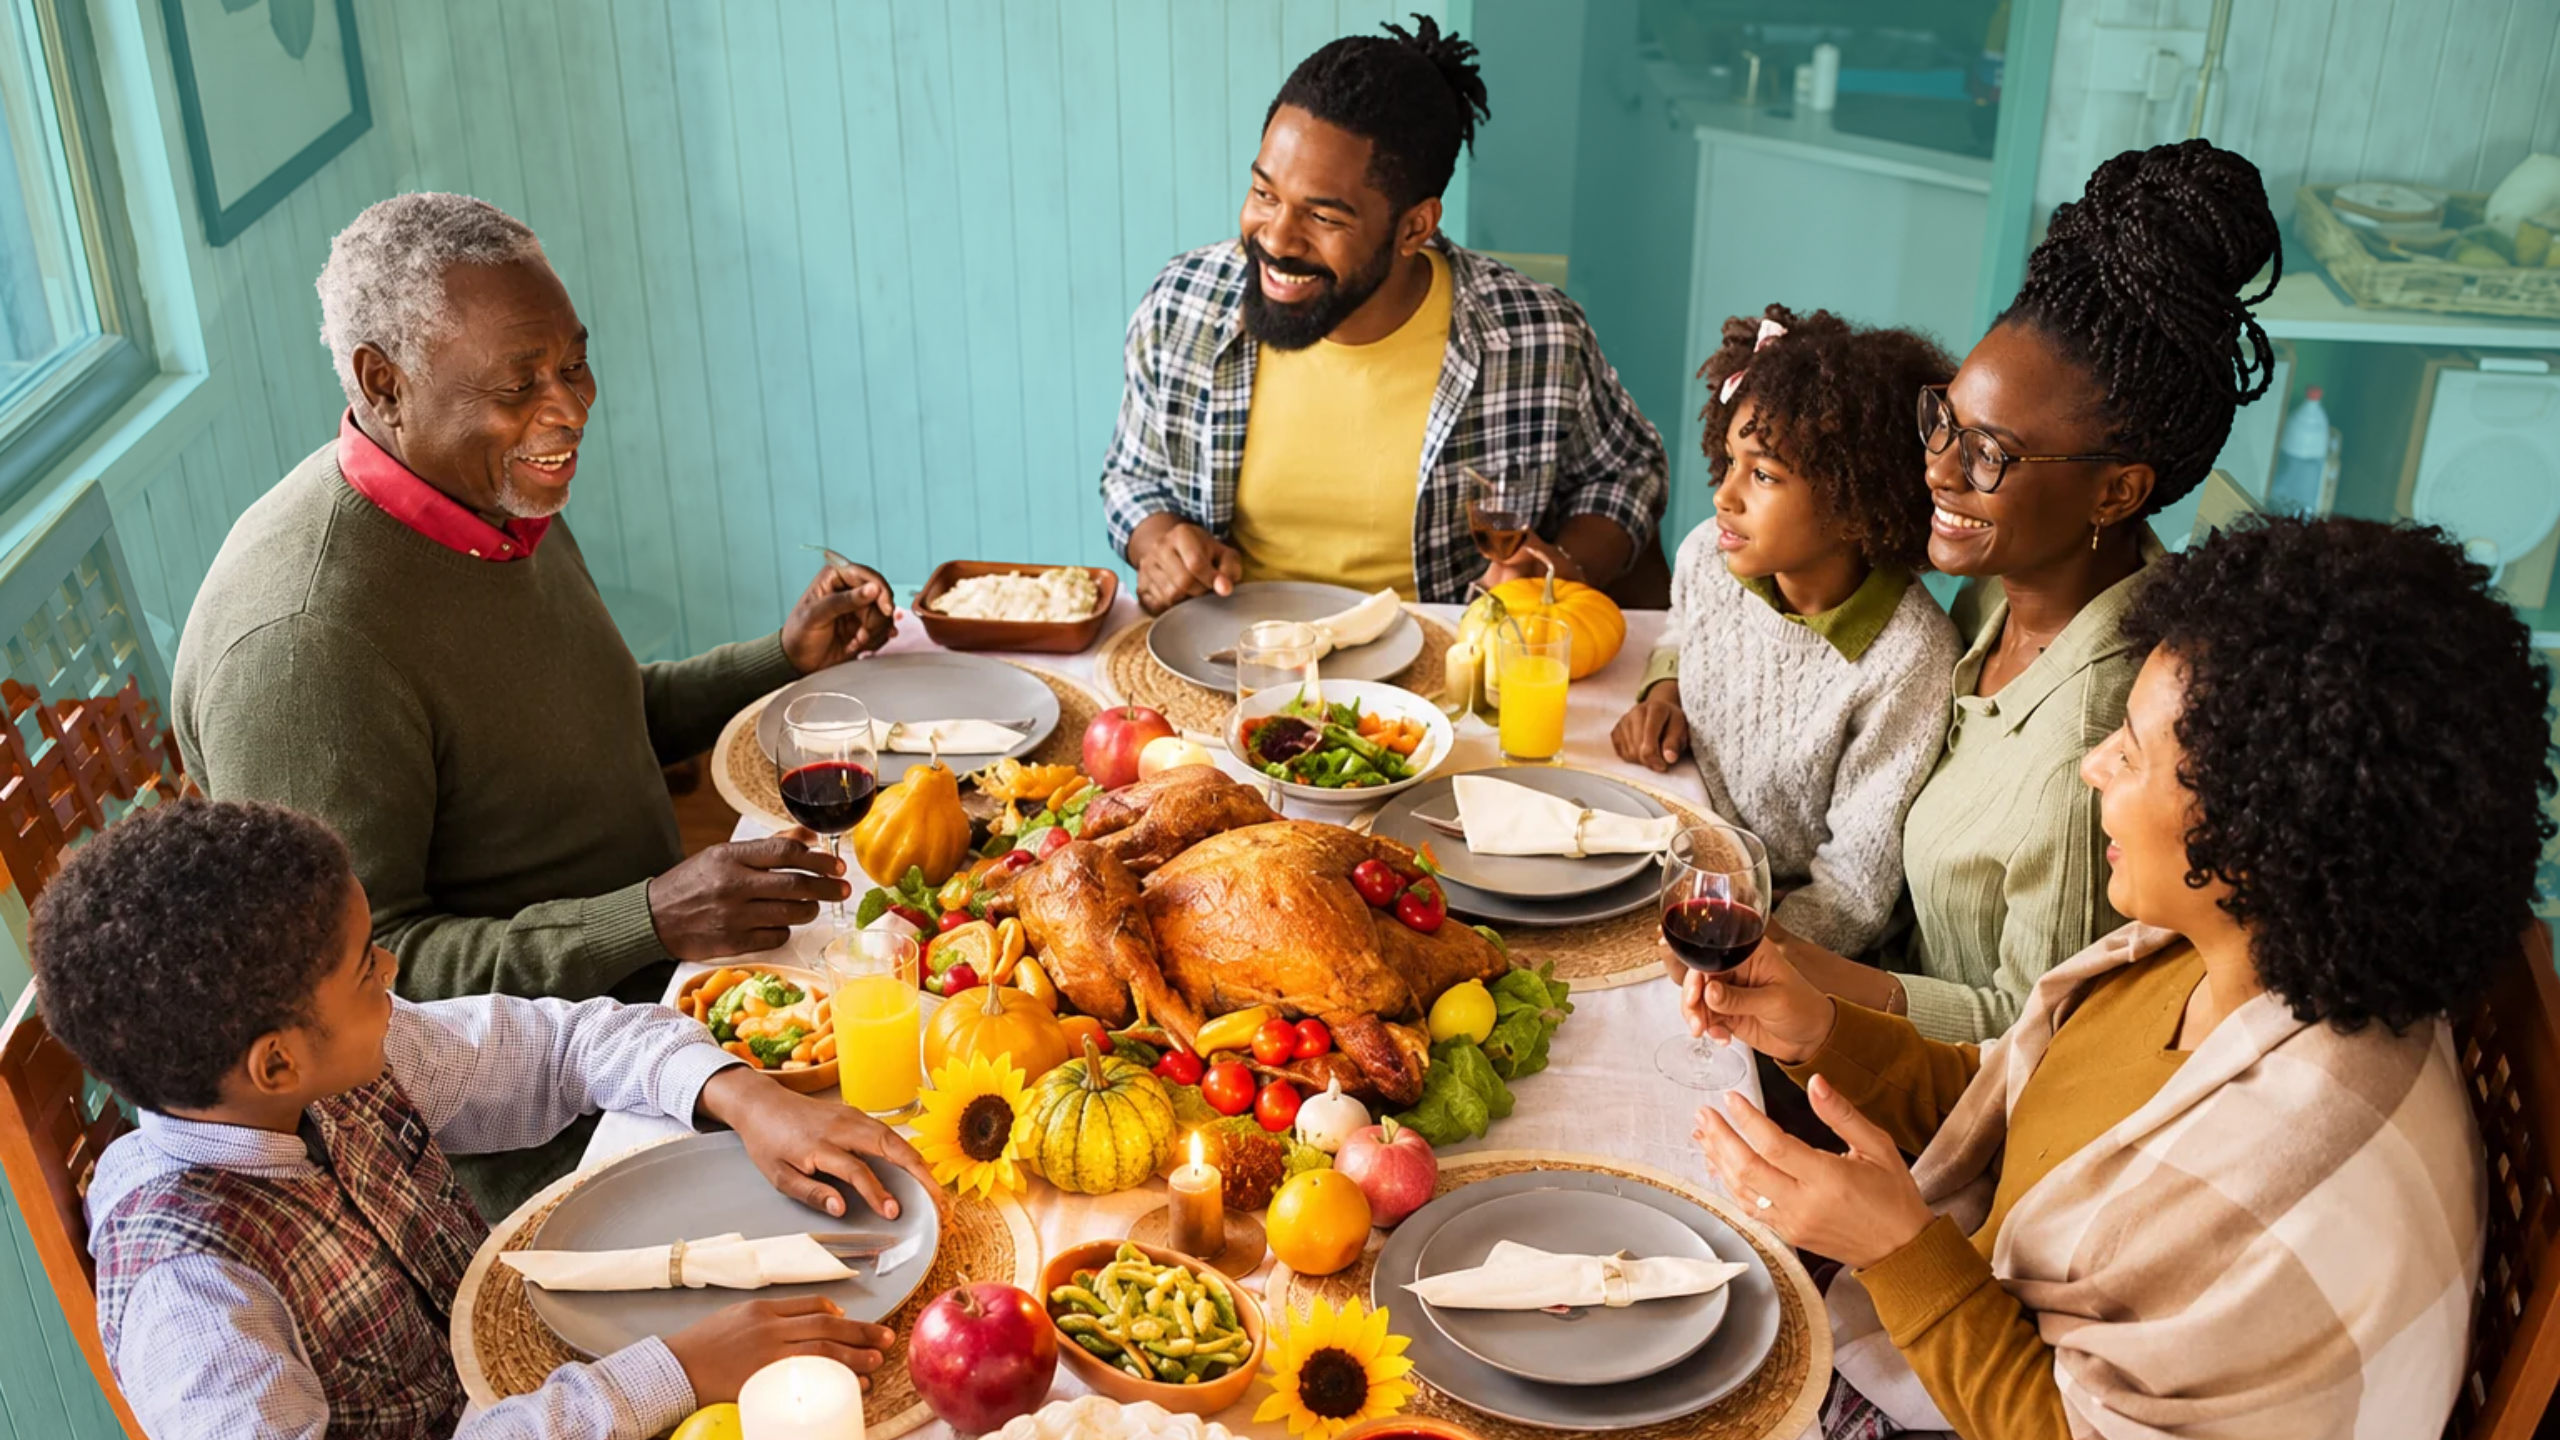
Thanksgiving has a way of turning into a housing conversation. Someone mentions what they’re paying in rent, someone else mentions what they’ve saved, and before dessert a sibling or cousin asks, “What if we just bought something together?”
Plenty of people would say yes. In a September 2026 Neighbors Bank survey of 1,014 U.S. adults, 41% said they’d consider co-buying a home with a sibling and 44% with a parent if it made ownership more affordable.
The numbers are only the beginning. As Pairgap founder Nikki Merkerson puts it, “Family doesn’t automatically make someone a good co-owner.” Trust gets you to the table. It won’t tell you who pays when the water heater dies, what happens if your brother takes a job across the country or how you split the equity when one of you put in twice as much.
These are the conversations to have before Thanksgiving dinner turns into a deal.
Can You Buy a House With a Sibling or Other Family Member?
Yes. More than one person can apply for a mortgage together, and more than one person can be on the deed. Family members co-buy the same way friends and unmarried partners do.
Before you make an offer, agree on five things:
- How much each person puts in, and what that money buys them
- What share of the home each person owns
- Who lives there and who pays for what
- How you make big decisions
- What happens if someone wants out, can’t pay or dies
It also helps to know that the loan and the deed do different jobs. The loan documents determine who’s responsible for the debt. The deed identifies the legal owners. A co-borrower may be responsible for the full debt even if the co-owners agreed to split payments. Freddie Mac notes that every co-borrower is liable for the regular payments, and if one can’t pay, someone else has to cover the full amount to avoid default.
Confusing these two roles can create serious disputes later, especially when co-owners’ contributions and ownership shares differ.
When Can Buying a House With Family Work Well?
Pooling savings can widen what you’re able to consider. Two people with $50,000 each can compete with someone who has $100,000.
Lenders don’t simply add your incomes together, though. Freddie Mac explains that they review combined income, assets, debt-to-income ratios and credit scores, and each loan program has its own requirements. Your cousin’s car loan and credit history come along with her paycheck. Shared ownership also means shared debt, shared repair bills and shared risk.
Family co-buying tends to hold up better when these things are true:
- Everyone can afford their share with room to spare, not just on paper
- You agree on what the home is for: a place to live, a rental, a home for a parent or a long-term investment
- You agree on roughly how long you’ll own it
- You’re willing to put the decisions in writing before you buy
Nikki bought her first property with a coworker, and it changed her path. It also taught her that the partnership has to work, not just the money.
What Should You Talk About Before You Commit?
Skip “Are we on the same page?” Everyone says yes to that one. Ask questions that need a specific answer.
Money and readiness
- What’s each person’s income, monthly debt and credit picture?
- How much can each of us put toward the down payment and closing costs?
- If one of us lost income tomorrow, could the rest cover the full payment for three to six months?
- How much will we keep in reserve for repairs, insurance deductibles and tax bills?
The property plan
- Who’s going to live there?
- If we rent out a unit or a room, do the numbers still work with a month or two of vacancy?
- Does each of us plan to own it for three years, ten years or longer?
If you’re thinking like an investor and your sister wants a stable home with no changes, you’ll disagree about every renovation, tenant and refinance offer. Settle that now.
How you’ll work together
- Who pays the bills and tracks what everyone contributed?
- How much can one person spend on a repair without asking the others?
- What happens if one of us thinks the other isn’t pulling their weight?
If you can’t discuss money, risk and disagreements openly before buying, resolve that before committing to shared ownership. The Real Estate Partner Test can help start the conversation. Each of you answers 25 questions, and comparing your results shows where you approach partnership differently.
How Should You Handle Money, Ownership and Responsibilities?
Here’s a hypothetical. Two cousins buy a duplex. One puts $30,000 toward the down payment. The other puts in $10,000 but has the stronger income and credit, so the loan approval leans more on her application. They take the title 50/50 because it feels fair and simple.
Three years later, the first cousin wants his extra $20,000 back before they split anything. The second cousin points to the deed.
Her stronger income and credit don’t automatically give her a larger or smaller ownership share. His bigger check doesn’t either. What matters is what they agreed to and wrote down, and they never wrote anything down. Their agreement should have said how the extra $20,000 is treated, and they should have checked whether the title and loan arrangements matched what they intended.
For every contribution, ask:
- Is this a gift, a loan or a bigger ownership share?
- If it’s a loan, when and how does it get paid back?
- Do the deed and the loan reflect what we agreed?
Then ask a local real estate attorney how to hold the title. Joint tenancy usually involves equal shares and a right of survivorship, so when one owner dies, their share typically passes to the surviving owners. Tenancy in common can allow unequal shares, and an owner’s interest may pass under their will or, without one, under their state’s inheritance laws. The rules depend on your state and how the deed is written, so questions to bring include:
- Which form of title fits our contributions and our plans?
- What happens to each person’s share if one of us dies?
- Can we hold unequal shares, and how would that be recorded?
Finally, agree on how you’ll split the ongoing costs (mortgage, taxes, insurance, utilities and maintenance) and what happens when a payment is late.
What Happens When Someone Wants Out?
Eventually, someone might. A new job, a marriage, a divorce or a move can turn a long-term plan into a short-term one.
In many states, a co-owner who can’t reach an agreement can ask a court to divide the property or order a sale through a partition action. Whether that’s available, how it works and what a court can order vary by state. A court proceeding can be costly and may leave the parties with less control over the outcome.
A written exit plan gives you another path. It should answer:
- How much notice does someone need to give before leaving?
- How will the home be valued? A jointly chosen appraiser is a common choice.
- Do the remaining owners get the first chance to buy the share?
- How long do they have to come up with the money or refinance?
- What happens if nobody can afford the buyout?
Talk about death and incapacity too. It’s uncomfortable at a holiday table, which is why people skip it. In the Neighbors Bank survey, 36% wanted a co-buying agreement to spell out what happens if the relationship ends, but only 21% wanted it to address what happens if someone dies. Ask your attorney how your title choice and each person’s estate plan work together.
What Are the Most Common Family Co-Buying Mistakes?
Treating a handshake as the plan. Family trust makes a written agreement feel unnecessary. Write it anyway, because life changes even when the trust doesn’t.
Calling money “help” without defining it. When a parent or older sibling covers part of the down payment, nobody wants to ask whether it’s a gift, a loan or a stake in the house. Ask before closing, and write down the answer.
Letting old family roles make the decisions. If the oldest sibling has always called the shots, that habit will follow you into the house. Agree on which decisions need everyone’s sign-off.
Your Family Co-Buying Checklist
Before anyone signs a purchase contract, you should be able to check off every item:
- A written record of what each person is contributing, and whether it’s a gift, loan or ownership share
- Ownership percentages everyone agrees on
- A title choice reviewed with a local real estate attorney
- Who will live in the home, and the rules for guests or new residents
- How mortgage, taxes, insurance, utilities and repairs get split
- A monthly reserve amount
- A dollar limit for repairs one person can approve alone
- What happens if someone can’t pay their share, and how long the others will cover it
- Which decisions need everyone’s approval
- How the home will be valued if someone leaves
- A first-chance-to-buy rule for remaining owners
- What happens if a co-owner dies or can’t make decisions
- How you’ll settle disagreements before anyone calls a lawyer
- A written co-ownership agreement, reviewed by a local real estate attorney before closing
When you’re ready to put these decisions in writing, the Real Estate Prenup walks co-buyers through ownership, contributions, repairs, decisions and exit terms.
How Do You Know If You’re Ready to Co-Buy With Family?
You’re in a stronger position when everyone can answer the checklist honestly, document the decisions and agree on what happens when circumstances change.
Run the numbers with the Co-Buyer Calculator to see your combined buying power. Then test that number against a big repair, a vacancy or a few lean months.
Before “we should buy something together” turns into an offer, find out how each of you approaches partnership.